SF Chronicle: Impact of Voting on California Props 40, 41, and 42
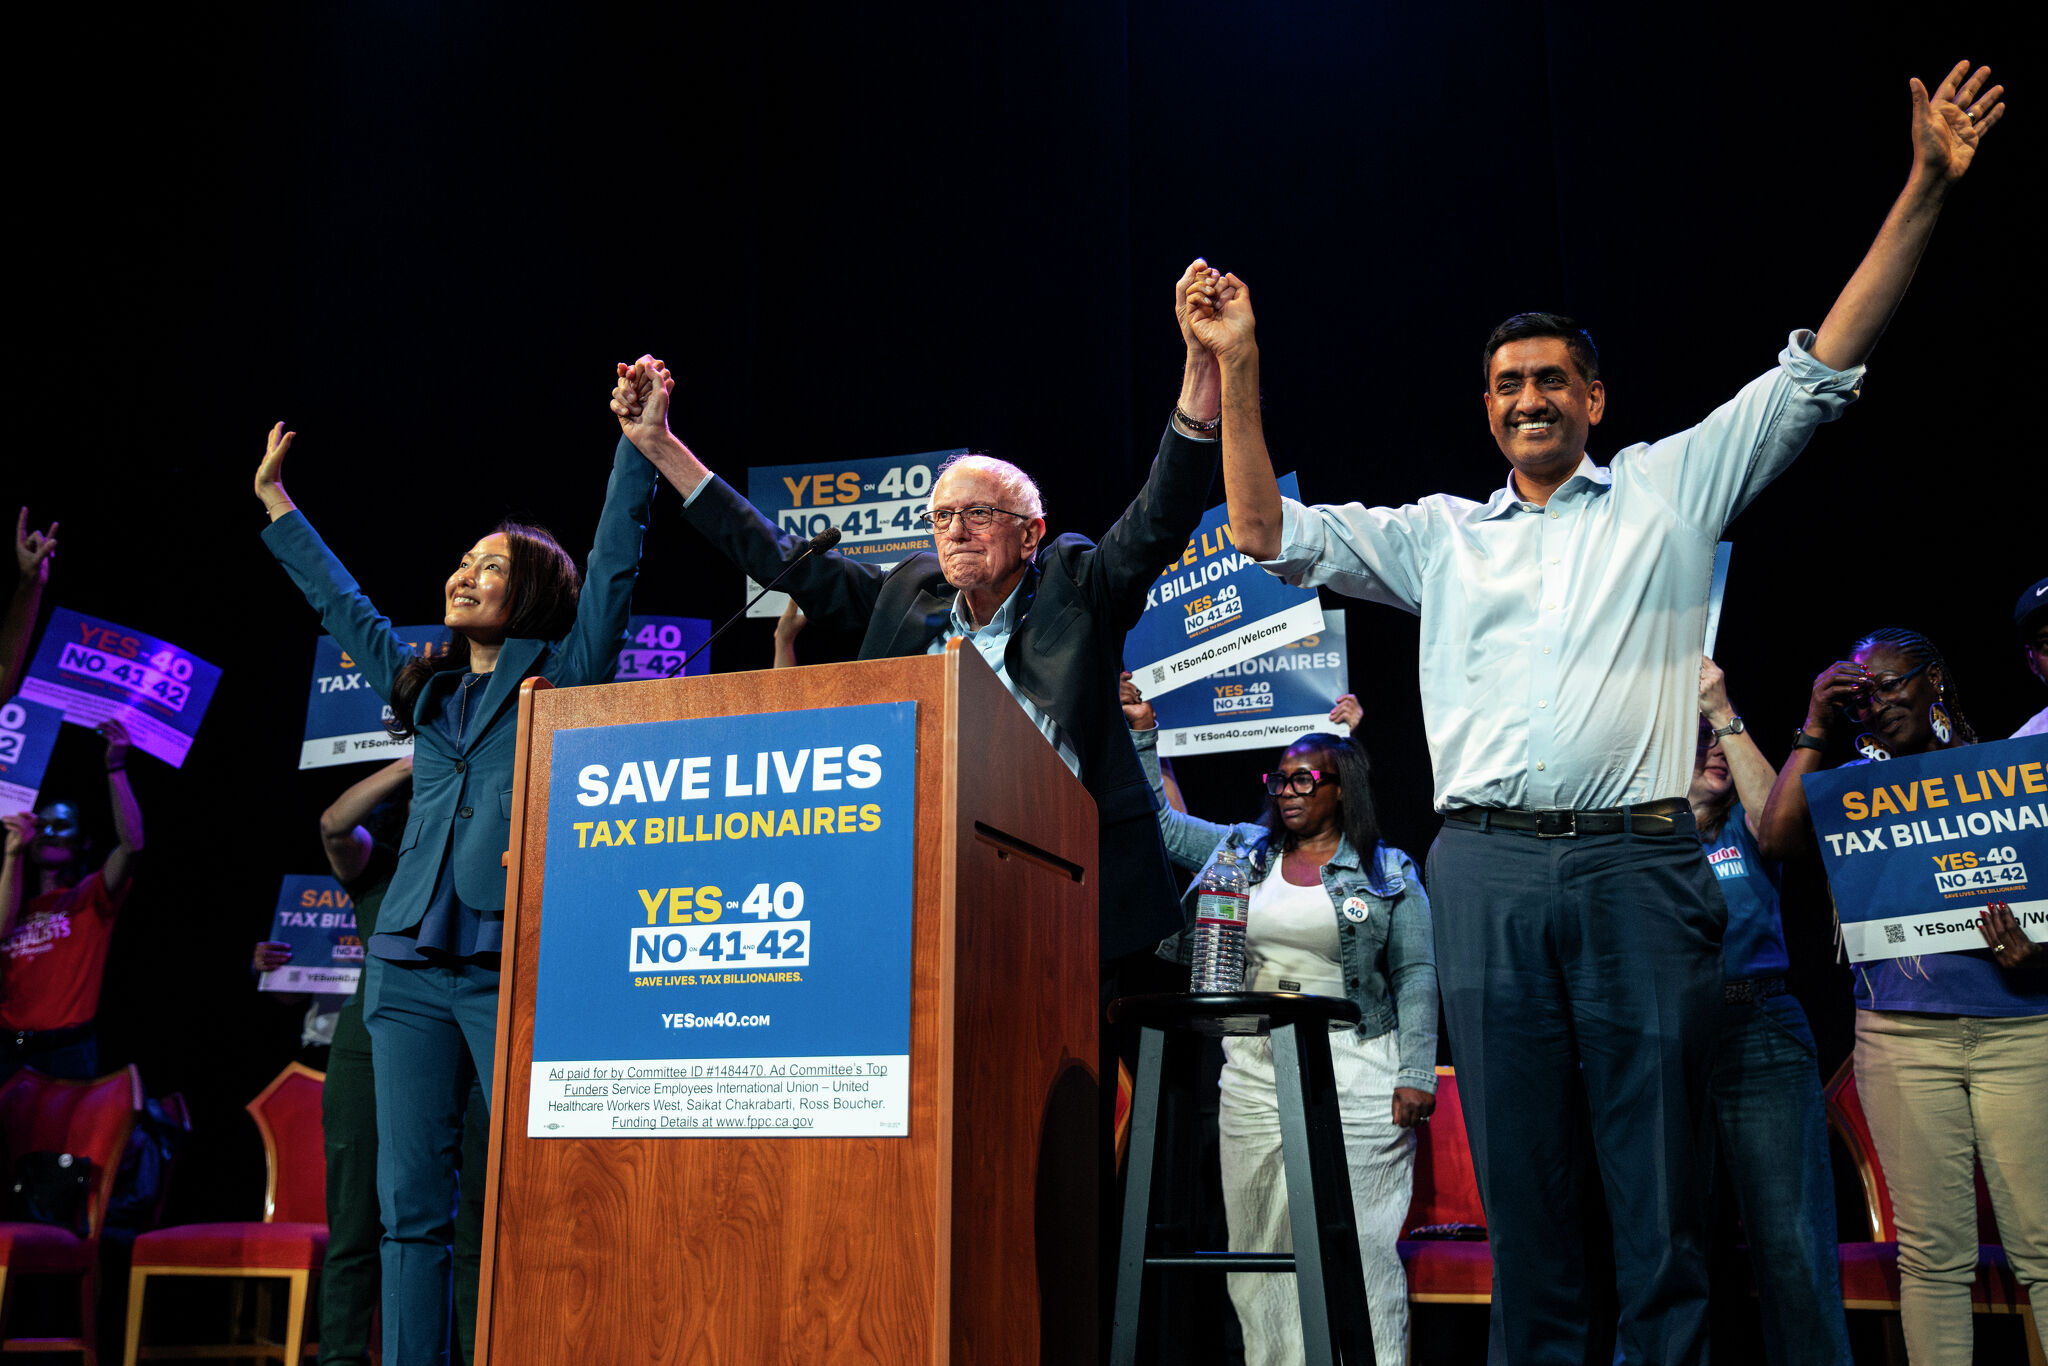
Proposition 40, the 2026 Billionaire Tax Act, faces direct conflicts on the November ballot from competing measures Proposition 41 and Proposition 42, creating a complex legal and fiscal puzzle for California voters, the San Francisco Chronicle reported in October 2026. Under the California Constitution, if two conflicting measures pass with more than 50% of the vote, the one receiving the highest number of affirmative votes prevails.
Voters casting ballots on these measures must weigh contrasting fiscal approaches. Proposition 40 would impose a one-time wealth tax on the net worth of people who were California residents as of January 1, 2026, and had more than $1 billion in net worth as of December 31, 2026.
Proposition 41 would outlaw new taxes passed after January 1, 2026, that are exempt from the Gann limit, effectively nullifying Proposition 40 according to a paper co-authored by measure drafters. Proposition 42, titled the Retirement and Personal Savings Protection Act of 2026, would bar taxes enacted after January 1, 2026, on personal property, savings, and retroactive residency-based wealth taxes.

Ballot Mechanics and the Conflict of Majority Rules
Backers of the billionaire tax urge voters to approve Proposition 40 while rejecting Propositions 41 and 42. Straightforward outcomes occur if voters follow this guidance or adopt the exact opposite stance. If Proposition 40 clears the 50% threshold while Props 41 and 42 fail, the wealth tax takes effect. If Proposition 40 loses and either competing measure passes with a simple majority, the billionaire tax fails.
Complications arise if Proposition 40 and either Prop 41 or 42 all exceed 50% approval. Under established constitutional rules, whichever measure secures the higher raw vote count prevails entirely, rendering the conflicting provisions of the runner-up null and void. Fredric Woocher, an election law attorney with Stumwasser and Woocher, noted in the Chronicle report that competing propositions have become an increasingly common technique used by special interests to confuse voters and defeat measures they oppose.
Historical precedent confirms this legal threshold. In June 1988, two competing campaign finance measures, Proposition 68 and Proposition 73, both passed with majorities. The California Supreme Court ultimately ruled in 1990 that only the provisions of the measure receiving the highest number of affirmative votes could be enforced.
Legal Challenges and Audit Mandates on the Horizon
Legal battles are widely anticipated regardless of the November outcome. Proposition 40 includes a procedure for expedited judicial review to handle expected challenges. Meanwhile, Proposition 41 introduces strict audit requirements, mandating that the state auditor conduct preelection financial and performance reviews for citizen-sponsored special taxes once petitions reach 25% of required signatures, followed by four-year reviews.
Kaye, a co-drafter of Proposition 40, contends that these audit provisions do not conflict with the wealth tax and would stand regardless of vote totals. Darien Shanske, a UC Davis law professor and co-drafter of Proposition 40, disputes that view, telling the Chronicle there would be a fight over whether those provisions could survive independently.
If all three measures fail—an outcome consistent with historical data showing California voters approve roughly 35% of initiatives—current fiscal policies remain unchanged. As the November election approaches, corporate legal teams and tax advisory services are preparing for extensive courtroom battles to interpret the interplay between the competing ballot measures.