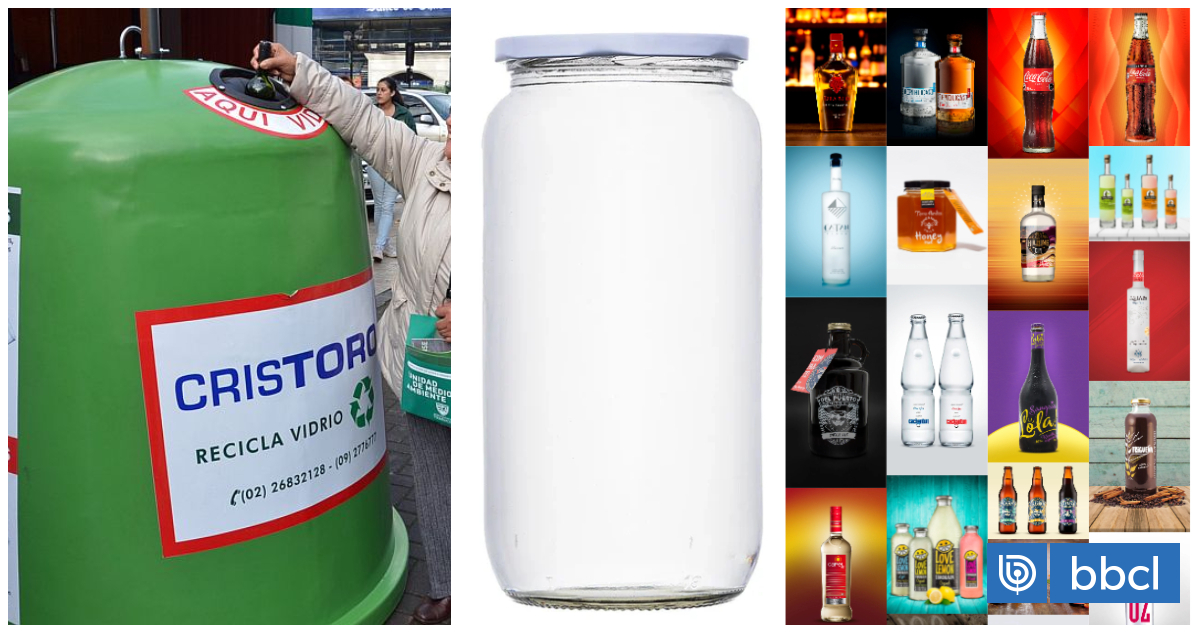
Desde garrafas a famosos envases: Firma europea sella compra de cristalería chilena con más de 70 años | Economía
Vidrala S.A. Has finalized the 100% acquisition of Chilean glass manufacturer Cristalerías Toro (Cristoro) for €75 million, rebranding the entity as Vidrala Chile. The deal consolidates Vidrala’s footprint in Latin America, leveraging Cristoro’s 70-year legacy to capture growing demand in the wine and beverage sectors. With a net debt-to-EBITDA ratio capped at 0.5x, the transaction underscores a strategic push toward sustainable packaging consolidation in emerging markets.
The Valuation Mechanics: Analyzing the €75 Million Entry Point
The closure of this transaction marks a definitive end to Cristoro’s seven-decade run as a family-owned entity, transitioning the asset into the portfolio of one of Europe’s largest glass packaging groups. From a valuation standpoint, the €75 million enterprise value presents a compelling entry multiple for Vidrala. Based on Cristoro’s reported fiscal performance—generating approximately $79.9 billion CLP in revenue and an adjusted EBITDA of $13.2 billion CLP—the deal implies an EV/EBITDA multiple in the range of 5.5x to 6.0x, assuming standard FX conversions for the 2026 fiscal year.
This pricing structure is aggressive yet prudent for the packaging sector, where capital expenditure requirements for furnace maintenance and energy efficiency upgrades often compress free cash flow. Vidrala’s ability to absorb the debt while maintaining a net leverage ratio of merely 0.5 times annual EBITDA signals a robust balance sheet, a critical buffer against the volatility of natural gas prices that dictate glass manufacturing margins.
Strategic Rationale: The “Definitive Material” Thesis
Raúl Gómez, CEO of Vidrala, framed the acquisition not merely as a capacity expansion but as a ideological commitment to glass as the “definitive packaging material.” This rhetoric aligns with broader macroeconomic shifts where global financial markets are increasingly penalizing single-use plastics through carbon taxation and regulatory headwinds. By securing Cristoro’s established relationships with the Chilean wine and cosmetic industries, Vidrala effectively purchases immediate market share in a region where recycling infrastructure is already mature; Cristoro pioneered glass recycling bells in the country as early as 1997.
However, integrating a legacy family business into a multinational corporate structure introduces friction. The operational overhaul required to align Cristoro’s legacy systems with Vidrala’s industrial model will demand rigorous change management. What we have is precisely the juncture where mid-market competitors often falter, necessitating the engagement of specialized M&A advisory firms to navigate the cultural and operational integration phases without disrupting supply chain continuity.
“The consolidation of the glass packaging sector in Latin America is inevitable. Investors are looking for scale to justify the CAPEX required for decarbonization. Vidrala’s move secures their position as the low-cost producer in the Andes region.”
Supply Chain Entropy and Logistics Optimization
Glass is a heavy, low-value-density commodity, making logistics the primary arbiter of profitability. The “weight-to-value” ratio means that transportation costs can erode margins faster than raw material fluctuations. Vidrala’s acquisition allows for the optimization of distribution networks across the Southern Cone, reducing the carbon footprint per unit delivered—a key metric for ESG-focused institutional investors.
To realize these synergies, the new Vidrala Chile entity will likely need to restructure its outbound logistics contracts. This creates an immediate opportunity for enterprise logistics providers capable of handling heavy industrial freight with precision. The goal is to minimize “empty miles” in the return loop of recycling, a complex logistical puzzle that requires real-time data integration between collection points and manufacturing furnaces.
The Fiscal Horizon: Debt Management and Capital Allocation
The press release highlights a “solid financial position” post-acquisition. In an environment where central banks may be navigating the tail end of a tightening cycle, maintaining low leverage is a defensive moat. Vidrala’s disciplined approach to debt ensures they retain the liquidity necessary to invest in furnace technology upgrades, which are critical for meeting the stringent emissions standards expected in the 2027-2028 fiscal windows.
For stakeholders monitoring the sector, the key indicator to watch is not just revenue growth, but the EBITDA margin expansion resulting from operational efficiencies. If Vidrala can lift Cristoro’s margins from the current ~16.5% toward the group’s average of 20%+, the €75 million entry price will look like a bargain in retrospect. This financial engineering often requires the expertise of corporate finance consultants who specialize in post-merger cost rationalization and working capital optimization.
Market Trajectory: The Consolidation Wave
This deal is not an isolated event; it is a symptom of a broader consolidation wave sweeping the industrial packaging sector. As sustainability mandates tighten, smaller, family-owned manufacturers lack the capital scale to transition to green hydrogen or electric melting furnaces. They become acquisition targets for giants like Vidrala, O-I Glass, or Ardagh Group.
For the World Today News Directory reader, the implication is clear: the B2B service landscape must pivot to support this consolidation. Legal firms specializing in cross-border industrial transactions, ESG compliance auditors, and heavy-industry logistics coordinators are the primary beneficiaries of this trend. As Vidrala Chile begins its new chapter, the focus shifts from the handshake to the hard work of integration, where the true value of the deal will be forged in the furnace of execution.