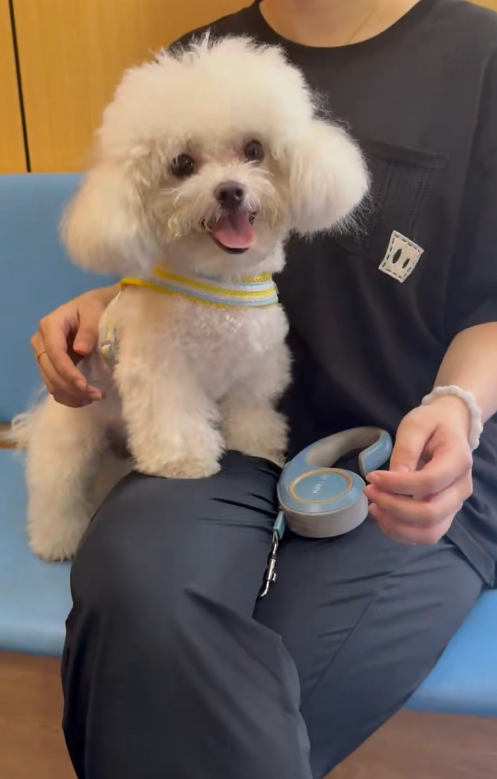
Guotai Property and Casualty denies pet insurance claim in Nanchang
In Nanchang, a pet owner’s attempt to claim medical expenses for her Bichon Frise from Guotai Property And Casualty Insurance Co., Ltd. was denied on August 27, after the insurer claimed the illness linked back to a pre-waiting-period incident, highlighting broader consumer friction over pet policy exclusions.
The Claim Rejection and Policy Terms
In June, Ms. Hu purchased a monthly pet insurance policy for her Bichon Frise, named Xiao Qi, from Guotai Property And Casualty Insurance Co., Ltd. for 38.25 yuan per month under an upgraded plan. The policy terms covered both accident and illness medical insurance, with single-accident limits set at 1,200 yuan for outpatient care and 2,000 yuan for surgery after the completion of a waiting period.
On August 2, Xiao Qi developed symptoms including a limp, shivering limbs, and a fever. Hu brought the pet to a veterinary hospital where exams yielded diagnoses of unknown-origin pain, respiratory mycoplasma, and severe inflammation. Total treatment costs exceeded 2,000 yuan. When Hu submitted a claim through the online portal, Guotai Property And Casualty Insurance Co., Ltd. returned an audit failure on August 27. The insurer stated that the symptoms appeared prior to the expiration of the waiting period and cited policy exclusions regarding pre-existing conditions present before policy activation.
Consumer Complaints and Insurer Response
Hu disputed the rejection, noting that a prior incident on July 29—where Xiao Qi ate an un-refrigerated canned food item and experienced diarrhea—was entirely unrelated to the subsequent respiratory mycoplasma infection. While the insurer asserted that the illness carried an incubation period linking back to the July incident, Hu stated that the company failed to provide supporting medical evidence. Public complaint platforms like Black Cat show numerous similar grievances regarding Guotai Property And Casualty Insurance Co., Ltd., with policyholders reporting instances where insurers allegedly stretched pre-existing condition exclusions based on minor historical symptoms to deny full payouts. As of late September, Guotai Property And Casualty Insurance Co., Ltd. has not responded to media inquiries regarding Hu’s case.
Legal Perspective on Insurance Exclusions
Regarding the validity of the insurer’s rejection, Jiangxi Huagang Law Firm lawyer Zhu Rong stated that denying payout under these circumstances lacks factual and legal backing, running counter to provisions of the Insurance Law. Under Article 17 of the Insurance Law, format clauses regarding exclusions must be explicitly and clearly explained to the policyholder to hold legal binding force. Article 30 stipulates that ambiguities in format terms should be interpreted in favor of the policyholder. Legal experts suggest that if insurers wish to deny claims based on pre-existing conditions or incubation periods, concrete diagnostic proof linking the prior event to the current medical condition must be supplied.

Disclaimer: The views and cultural analyses presented in this article are for informational and entertainment purposes only. Information regarding legal disputes or financial data is based on available public records.