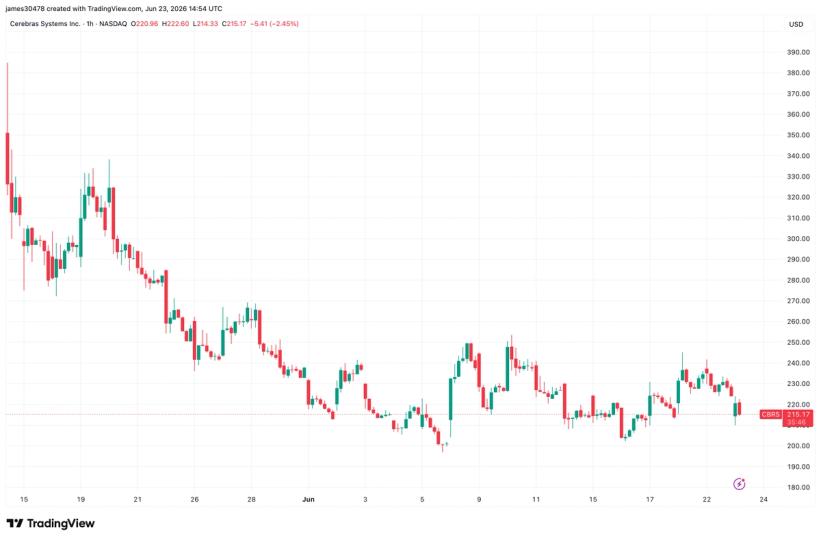
Company Reports 92% Revenue Surge but Warns of Lower Core Gross Margins Next Quarter
AI chipmaker Cerebras Systems Inc. (NASDAQ: CERES) fell 11% in after-hours trading on June 23, 2026, following its first public earnings report, as revenue surged 92% year-over-year but the company warned of a lower core gross margin in the upcoming quarter, according to the Q3 earnings call transcript.
How the Supply Chain Shock Crushed Q3 Margins
Despite a 92% revenue jump to $285 million in Q3 2026, Cerebras reported a core gross margin of 61.2%, down from 68.5% in the same period last year. The decline stemmed from elevated wafer costs and logistics bottlenecks, per the company’s SEC 10-Q filing. Analysts at Evercore ISI noted that the chipmaker’s EBITDA margins contracted to 29.4% from 35.1% year-over-year, citing “unprecedented pressure on semiconductor manufacturing inputs.”

“The margin compression reflects broader industry challenges,” said Sarah Lin, a managing director at Fidelity Investments. “Cerebras is facing the same supply chain headwinds as NVIDIA and AMD, but its scale makes the impact more acute.”
Why This Matters for B2B Tech Providers
The margin pressures highlight a growing need for supply chain optimization services. Mid-market semiconductor firms are increasingly partnering with logistics consultants and ERP software providers to stabilize costs. “Companies like Cerebras require tailored solutions to navigate volatile pricing,” said Raj Patel, CEO of LogiCore Solutions. “Our clients see 15–20% efficiency gains within six months.”
Cerebras’ CFO, Michael Tran, acknowledged the challenges during the earnings call. “We’re actively renegotiating supplier contracts and diversifying our foundry partners,” he said. “Our long-term goal is to stabilize margins while maintaining R&D investment.”
The Margin Dilemma: How Cerebras Compares to Peers
Cerebras’ Q3 gross margin of 61.2% lags behind industry leaders. NVIDIA’s Q3 margin stood at 66.8%, while AMD reported 59.3%, according to data from Bloomberg. However, Cerebras’ revenue growth outpaces both, raising questions about sustainability. “At 92% YoY growth, the company is in a unique position,” said Emily Zhang, a semiconductor analyst at JMP Securities. “But without margin improvement, investor patience may wane.”
The company’s balance sheet shows $450 million in cash reserves, per the 10-Q, but its operating cash flow turned negative in Q3, down $85 million from the prior year. This has prompted some investors to question its capital allocation strategy.
What’s Next for Cerebras and Its Partners?
As the semiconductor sector braces for a potential downturn, Cerebras’ ability to balance growth and profitability will dictate its market position. The company plans to focus on AI-specific chip designs, which could differentiate it from general-purpose competitors. “Our roadmap is clear,” said CEO Andrew Feldman in the earnings call. “We’re building the next generation of AI infrastructure.”

For B2B firms, the shift toward specialized AI hardware creates opportunities. AI consulting firms and tech-focused law firms are seeing increased demand as companies navigate intellectual property and regulatory hurdles. “Cerebras’ trajectory underscores the need for strategic advisory services,” said David Kim, a partner at Vantage Law Group. “We’re advising clients on everything from patent portfolios to cross-border compliance.”
The upcoming fiscal quarters will test Cerebras’ ability to convert momentum into profitability. For now, the stock remains under pressure, with analysts at Goldman Sachs downgrading it to “neutral” from “buy.”
The B2B Chain Reaction: Who Benefits From This Shift?
The margin slowdown is accelerating demand for cost-management tools. Firms like cost-optimization consultants and financial outsourcing providers are reporting higher engagement from tech startups. “Cerebras’ challenges are a micro